
CANADA T5 DIVIDEND CALCULATOR
Supported tax years: 2024, 2025 and 2026.
Calculate taxable dividend amounts and federal dividend tax credits for eligible and non-eligible dividends using our free Canadian T5 Dividend Calculator. Get an instant breakdown of T5 Boxes 10, 11, 12, 24, 25 and 26 based on Canada Revenue Agency (CRA) calculation rules.
Built for Canadian Corporations, Business Owners & Tax Professionals CA
✓ Box 24 — Actual dividend
✓ Box 25 — Taxable dividend
✓Box 26 — Federal dividend tax credit

Enter the actual amount of eligible or non-eligible dividends paid to a Canadian-resident shareholder.
The calculator will determine the applicable taxable dividend amount and federal dividend tax credit.
The results are intended to assist with preparing T5 slips and do not calculate the shareholder's final personal income tax payable.
What Is a T5 Statement of Investment Income?
A T5 Statement of Investment Income is a Canadian tax information slip used to report certain investment income, including dividends paid by Canadian corporations.
When a Canadian corporation pays taxable dividends to shareholders, it may be required to prepare and issue T5 slips and file a T5 information return with the CRA.
A T5 slip identifies the actual dividend paid, the taxable dividend amount and, where applicable, the federal dividend tax credit. The reporting requirements depend on the type of income, the recipient and applicable CRA filing rules.
Eligible vs. Non-Eligible Dividends in Canada
Canadian taxable dividends are generally classified as eligible or non-eligible dividends. The classification affects how dividends are grossed up and how federal dividend tax credits are calculated for individual shareholders.
Eligible Dividends
Eligible dividends are generally paid from corporate income taxed at the general corporate income tax rate, subject to the corporation's eligible dividend designation rules.
For Canadian-resident individuals, eligible dividends are grossed up by 38%, and the federal dividend tax credit is calculated using the applicable federal rate.
Non-Eligible Dividends
Non-eligible dividends are commonly paid from income taxed at the small business corporate tax rate.
For Canadian-resident individuals, non-eligible dividends are grossed up by 15%, and a different federal dividend tax credit calculation applies.
The corporation must determine the correct dividend designation before preparing the T5 slip.
How to Calculate T5 Dividend Amounts
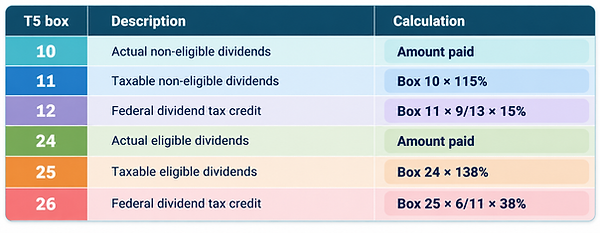
For dividends paid to Canadian-resident individual shareholders, the following calculations generally apply for 2024, 2025 and 2026.
These gross-up and credit calculations apply to Canadian-resident individual recipients. Corporate recipients have different reporting requirements and generally do not use the individual gross-up and dividend tax credit boxes.
Who Needs to Prepare a T5 Slip?
Canadian corporations that pay taxable dividends to shareholders may be required to prepare T5 slips and file a T5 information return with the CRA.
The requirement depends on the payment amount, income type and applicable reporting exceptions. A T5 slip is generally not required when the total reportable amount for a recipient is less than $50 for the calendar year, subject to exceptions.
For dividends paid to Canadian-resident corporations, the actual dividend amounts are generally reported in Box 10 or Box 24, while the individual dividend gross-up and federal dividend tax credit boxes are left blank.
When Is the T5 Filing Deadline?
T5 information returns are generally due by the last day of February following the calendar year in which the investment income was paid or credited. When the deadline falls on a weekend or recognized holiday, CRA's next-business-day rules may apply.
For 2026 dividend payments, the general filing deadline is March 1, 2027.
Frequently Asked Questions About T5 Dividends
FAQ
- 01
- 02
- 03
- 04
- 05
- 06